


If you own a business in Florida and you are a veteran, an active-duty service member or the spouse of one, FBDC’s VetLoan Advantage Plus program lowers the cost of an SBA 504 loan. FBDC pays half of the third-party lender fee, up to $3,000, and reduces its processing fee from 1.5% to 1.0%. The 504 loan itself is built for buying property or long-life equipment with a low down payment and a fixed rate. The program is a fee reduction on top of that structure.
This guide explains who qualifies, what the savings are, what a 504 loan can and cannot pay for, what a $500,000 loan might cost each month, and how to start.
Fbdc
fbdc.net
Lower 504 Fees for Veteran-Owned Businesses
FBDC’s VetLoan Advantage Plus reduces eligible SBA 504 fees for Florida veterans, service members, and spouses financing real estate or equipment.
Explore VetLoan Advantage Plus
VetLoan Advantage is a national concept run through the National Association of Development Companies (NADCO). Each participating certified development company (CDC) chooses which discounts it offers. NADCO lists examples such as the CDC paying half of the third-party lender fee, a cash rebate for professional fees such as appraisals and environmental reports, and a processing fee cut from 1.5% to 1.0%. What you receive depends on the CDC you work with.
FBDC’s version, VetLoan Advantage Plus, is described on its own program page. FBDC states it is the first CDC in Florida to take part in the NADCO program and extends the same benefits to veterans’ spouses. The published benefits are:
The processing fee is a percentage, so the dollar saving grows with the size of the loan. Ask FBDC to show the processing fee line on your own estimate, with and without the program, so you see the exact figure for your project. A full list of 504 closing costs is on the SBA 504 loan page, under approximate fees.
There are two layers of eligibility: the business, and the owner.
NADCO’s program description lists possible owner criteria, and each CDC sets its own. They include a veteran or active-duty owner with a minimum of 51% ownership, a veteran or active-duty owner with any ownership percentage, or the spouse of a veteran or active-duty applicant. FBDC says it extends benefits to veterans’ spouses, so a spouse-owned business is in scope. Confirm with FBDC how your ownership split is treated, especially if you have partners.
The 504 program has its own requirements. The SBA says eligible businesses must be operating, for-profit, located in the U.S., small under SBA size standards and not on the ineligible list. For the standard size test, the SBA describes tangible net worth under $15 million and average net income under $5 million after federal income tax for the two years before applying.
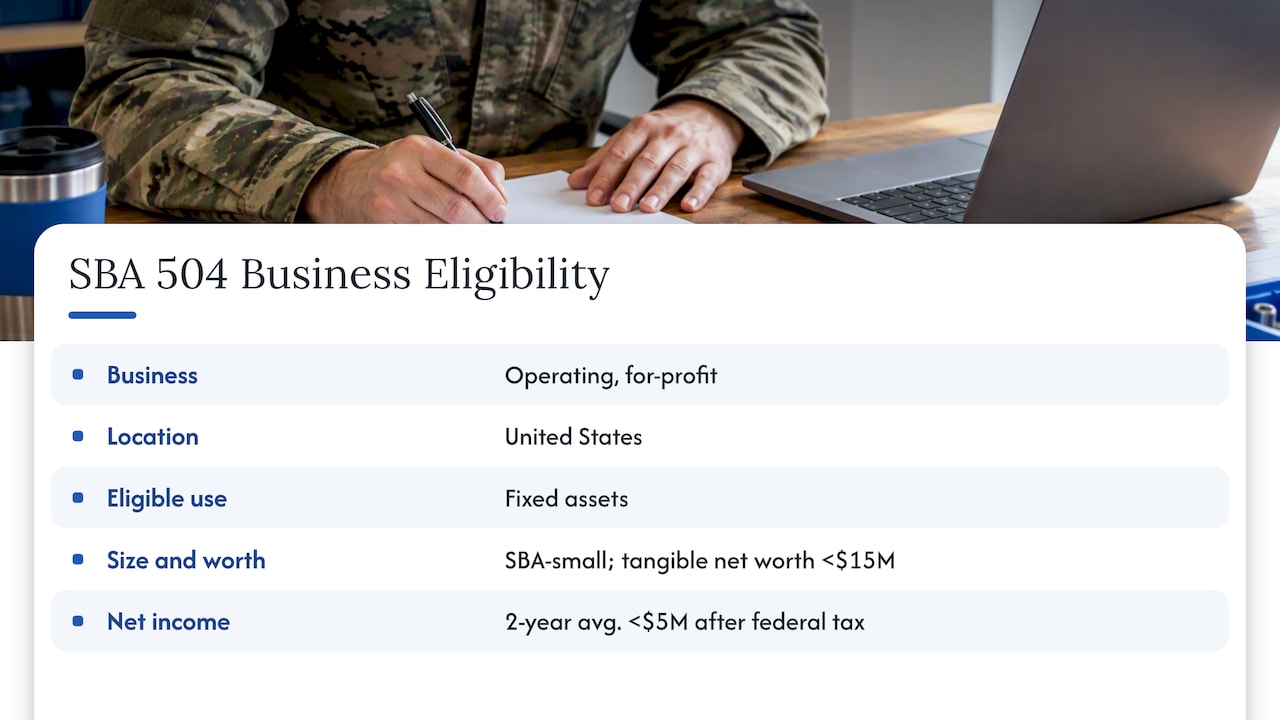
Two practical points follow from FBDC’s own lending focus. The business must be for-profit, so non-profits are out. And the loan must be for fixed assets, which brings us to the next section.
The SBA states that a 504 loan can fund the purchase, construction or renovation of existing buildings or land, and long-term machinery or equipment with at least 10 years of remaining useful life. That covers most things a growing Florida business wants to own:
The same SBA page is clear about what it does not cover: working capital, inventory and speculative investments. If your need is payroll or stock, a 504 loan is not the tool. If you are buying the building where you operate, it usually is.
Maximum amounts depend on the project type. A lender chart for the 2026 fiscal year shows maximum 504 debenture amounts from $5 million to $5.5 million, depending on the business or project. Most owner-occupied purchases by small businesses sit well below that.
FBDC runs several programs around the core 504 loan:
A common reader question is what the payment would be on a $500,000 SBA loan. The answer depends on the rate and the term, and neither is fixed until your loan is priced. What we can show is the arithmetic. These are illustrations using standard loan amortization, not quotes.
Loan amountTermIllustrative rateApprox. monthly payment$500,00025 years6.0%$3,221$500,00025 years7.0%$3,534
The numbers cover principal and interest only. They leave out the fees above, insurance, taxes and any part of the project financed by a different lender. A 504 project is usually split between a bank loan and the CDC portion, and each has its own rate, so your blended payment will differ. FBDC’s guide to 10, 20 and 25 year terms shows how term length changes the payment, and a long-term fixed rate on the CDC portion keeps that part from moving.
One more way to read the table: a 1-point difference in rate moves this payment by about $300 a month. A fee saving, by contrast, is a one-time reduction at closing. Both matter, and they are separate.
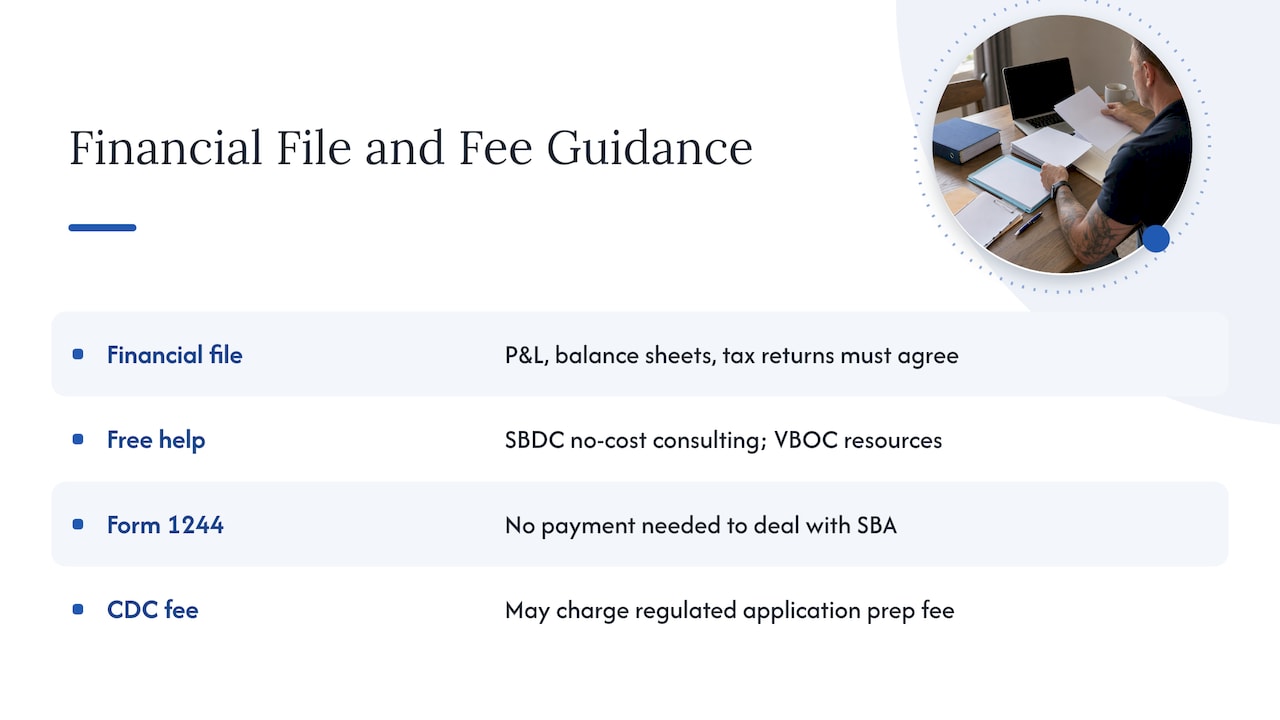
A clean file is the biggest factor in speed. Lenders look for consistent profit and loss statements, balance sheets and tax returns that agree with each other. This walkthrough of what lenders want in SBA financial statements lists the statements to prepare before you apply.
For free help, the Florida SBDC Network provides no-cost consulting that helps owners build business plans, understand their financials and prepare SBA 504 application packages. Veterans can also use Veterans Business Outreach Centers for counseling and resources.
One point from Form 1244 is worth knowing: it states that you do not need to pay anyone to deal with the SBA, and that a CDC may charge a fee under SBA regulations for preparing and processing an application. That is the processing fee the program reduces.
Most veterans comparing options weigh 504 against a conventional commercial mortgage and against the SBA 7(a) loan. 504 is designed for fixed assets. The National Association of Development Companies describes it as fixed-cost, long-term, SBA-backed capital meant to fill gaps in long-term small business financing. That makes it a natural fit when you are buying your location or a major machine and want a predictable payment for decades.
To compare side by side, see FBDC’s pages on 504 versus 7(a) and 504 versus a conventional commercial mortgage. If you are not sure which program matches your project, this overview of SBA loans in Florida walks through the choices. And if you wonder whether your earnings are enough, read how much income a business needs for a 504 loan.
Here is a hypothetical to show where the savings fall. A veteran who runs a landscaping company in Florida wants to buy the warehouse she currently rents. She also plans to renovate part of it.
The exact numbers depend on the purchase price, the appraisal and her financials. The point is that the fixed-asset costs and the working-capital costs are separated at the start, which keeps the application simple.
Our view: why we built VetLoan Advantage Plus
We have helped Florida small businesses close SBA 504 loans for over 35 years. In that time we have seen that veteran owners often have the discipline and the credit habits lenders want, but they pay the same closing costs as everyone else. Those costs, the appraisal, the environmental report and the processing fee, come due before the business has gained anything from the property.
That is why we pay half of the third-party lender fee, up to $3,000, and reduce our processing fee from 1.5% to 1.0%. We were the first CDC in Florida to join the NADCO VetLoan Advantage Program, and we extend the same benefits to veterans’ spouses because many spouses run the business while the veteran serves.
Our approach is simple. Tell us what you want to buy, and we will explain the structure, the fees and the timeline in plain terms. The 504 loan gives you a low down payment and a long-term fixed rate on the CDC portion. The program makes the closing lighter. Our staff works with you from the first call to funding, so there are no surprises late in the process.
PHENYX
If you own or are buying a Florida business and you or your spouse served, we can review your project and tell you whether it fits a 504 loan and how VetLoan Advantage Plus changes your closing costs. Start on the VetLoan Advantage Plus page, or see how we work across the state on our Florida 504 loans page.
Bring your tax returns, a draft purchase contract or an equipment quote if you have them. If you do not, we can begin with a conversation about the project.
FBDC describes VetLoan Advantage Plus as reduced SBA 504 loan fees for veteran-owned and military-spouse-owned small businesses in Florida. It is a 504 program. If you are weighing a 7(a) loan, the 504 versus 7(a) comparison explains how the two differ in uses and structure.
Start by deciding what you need to finance. For buildings, land or long-life equipment, an SBA 504 loan through a CDC is a strong route. You apply with tax returns, financial statements and projections, and the lender and CDC underwrite the file. Free counseling from the Florida SBDC Network or a Veterans Business Outreach Center can help you prepare.
Over 25 years, principal and interest would be about $3,221 a month at 6.0% and about $3,534 at 7.0%. Your actual payment depends on the rate, the term and how the project is split between lenders. FBDC can price your project once it knows the details.
Yes. FBDC states that it offers the VetLoan Advantage benefits to veterans’ spouses as well. NADCO’s program guidance also lists spouses of veterans or active-duty applicants among possible eligible owners. Confirm how your ownership is structured when you contact FBDC.
No. The SBA says 504 loans cannot be used for working capital, inventory or speculative investments. They finance real estate and equipment with a long useful life.

