


A CDC, short for Certified Development Company, is a community-based nonprofit certified and regulated by the SBA to originate SBA 504 loans alongside a private bank. If you plan to buy a building, build, renovate or finance long-lived equipment in Florida, the CDC provides the long-term, fixed-rate second-lien piece of the project that often makes the numbers work. Most owners start at the bank, and many never hear that the CDC exists.
Fbdc
Explore SBA 504 Financing in Florida
FBDC specializes in SBA 504 lending for Florida businesses acquiring real estate, heavy machinery, and equipment with low down payments.
CDC stands for Certified Development Company. CDCs are authorized by the SBA to originate 504 loans in collaboration with a senior lender. They are nonprofit, community-based partners whose purpose is economic development in the areas they serve.
The program itself is economic development financing designed to stimulate private-sector investment in long-term fixed assets, create or preserve jobs, and support small business growth and modernization. The name comes from Section 504 of the Small Business Investment Act of 1958. The scale is not small: in fiscal year 2021, the SBA approved 9,676 504/CDC loans totaling more than $8.2 billion.
The borrower is the for-profit business. The CDC is not the bank. It is a second, separate lender in the same deal, and that is why the program can lower the cash you need at closing.
The CDC handles the 504 part of the package from start to finish. The president of the national trade association for these lenders testified that CDCs work with the borrower to get SBA approval, make sure the loan is funded through private markets, and service it after closing.
In practice that means:
For more on how this lowers risk for the bank and speeds closing, see our guide to the certified development company role.
A typical 504 project has three parts, described in shorthand as 50-40-10:
PieceShare of project costLien positionBank (third-party lender)About 50%First lienCDC (SBA-guaranteed debenture)Up to 40%Second lienBorrowerAt least 10%Equity
This matches the federal regulation, which sets the borrower contribution at a minimum of 10 percent and the CDC loan at up to 40 percent.
The borrower share can be higher in some cases. The CDC contribution cannot exceed 35% for a business two years old or younger, or for a limited-market or special-purpose property, and cannot exceed 30% when both apply. That means a startup buying a special-purpose building should plan for more equity, up to 20%. Our guide on what startups must document covers that case.
A simple example: on a $2,000,000 project with standard terms, the bank would provide about $1,000,000, the CDC up to $800,000, and you at least $200,000. This is an illustration of the structure, not a quote.

Eligible uses include purchasing, constructing or renovating existing buildings or land, and refinancing qualified debt. Loans cannot be used for working capital or inventory. The OCC describes the program as for owner-occupied commercial real estate and long-term machinery or equipment.
Florida owners most often use it for:
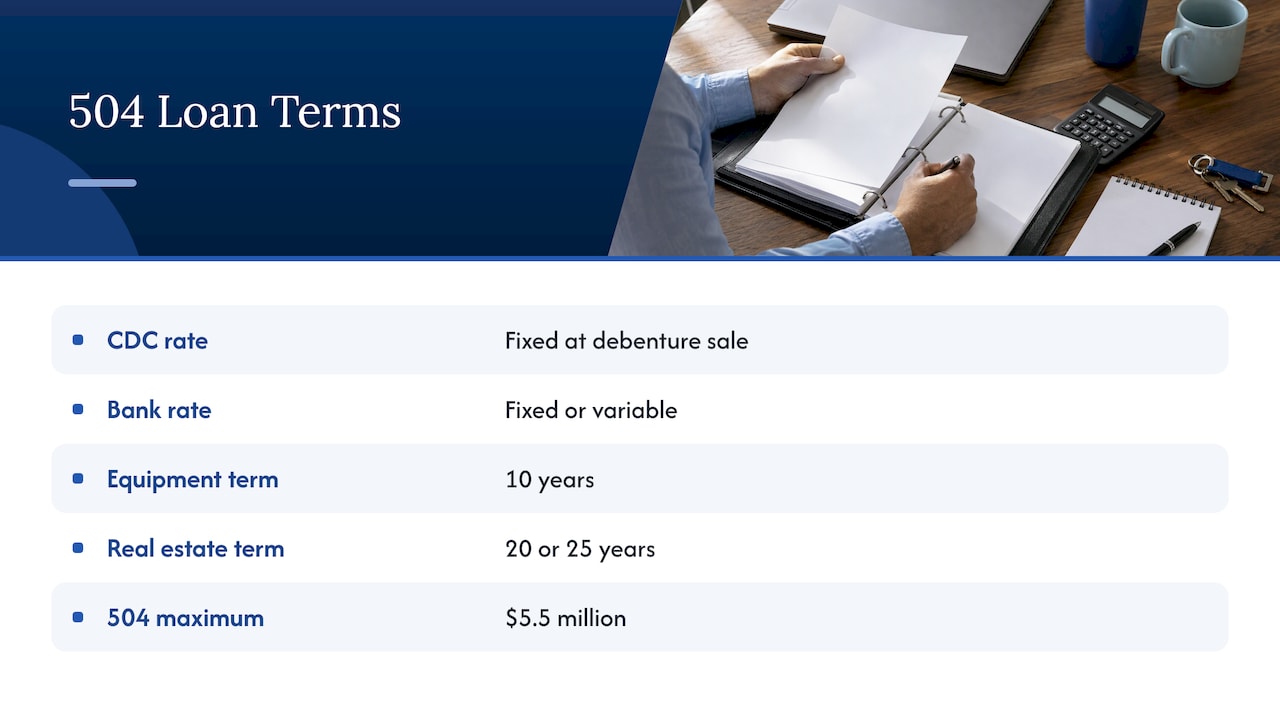
The CDC loan has a fixed interest rate set when the SBA sells the debenture, with a 10-year term (typically equipment) or a 20- or 25-year term (typically real estate). The SBA says rates are pegged to an increment above the current market rate for 10-year U.S. Treasury issues. A fixed rate with those terms lets an owner budget without worrying about rising rates or balloon payments on that portion.
The bank’s loan can be fixed or variable and is negotiated between you and the bank.
The maximum SBA 504 loan amount is $5.5 million. Eligibility also depends on the business: it must be an operating, for-profit, U.S.-based, small business with qualified management, a feasible plan, good character and the ability to repay. Our eligibility checklist for Florida walks through four checks before you call a CDC.
Federal rules cap what a CDC can charge. Under 13 CFR 120.971, the CDC may charge a processing fee of up to 1.5% of net debenture proceeds, a reasonable closing fee, and a monthly servicing fee of 0.625% to 2% per year on the unpaid balance. The SBA says closing costs total approximately 3% of the debt and may be financed with the loan. Our post on getting a real 504 fee number shows how to read a fee estimate. FBDC’s approximate fees are listed on our SBA 504 loan page.
Because 504 loans are available exclusively through CDCs, you start with one. Gather these items first, drawn from the SBA Form 1244 exhibit list:
Then you share these with the CDC, which prepares the credit memorandum and submits to the SBA. You will usually also talk to a bank about the senior loan, and your CDC can help coordinate that.
Our perspective
We have worked in SBA 504 lending for over 35 years, and the pattern is consistent: owners search for a “business loan” and talk only to banks. The CDC portion is where the low down payment and the long-term fixed rate come from, so we think it belongs in the first conversation, not the last.
Our approach is built around a faster, more streamlined process with experienced staff who guide you through each step. We also offer options around the standard structure: a bridge loan program for 504 projects, direct lending for smaller loans, and a program for veterans. Our aim is certainty about the path from application to closing.
If you are weighing a 504 against another SBA program, we have a comparison of SBA 504 vs. 7(a) to help you choose.
PHENYX
FBDC is a Florida-focused SBA 504 lender with down payments as low as 10% and long-term fixed rates. We handle standard 504 loans, refinancing, the 504 Velocity Bridge Loan, direct lending for smaller loans and VetLoan Advantage Plus for veterans.
To see how a project might be structured, start with our SBA 504 Loan Program page or find a team member through SBA 504 loans near you in Florida.
CDC means Certified Development Company. It is a nonprofit, SBA-certified organization that originates the 504 portion of a project loan. It works with a private lender and the borrower to finance land, buildings, machinery and equipment.
No. In a 504 project, a bank usually provides about 50% with a first lien, and the CDC provides up to 40% through an SBA-guaranteed debenture with a second lien. They work together in one financing package.
No. 504 proceeds are for fixed assets and qualifying refinancing, and cannot cover working capital or inventory. If your need is for fixed assets such as a building or equipment, a CDC is the right place to start.
The OCC fact sheet from 2018 counted about 217 CDCs nationwide. The SBA recommends finding a CDC in your area or contacting your local SBA office.

