


Yes, an SBA 504 loan can finance manufacturing equipment. SBA says the program covers long-term machinery and equipment with a useful remaining life of at least 10 years, including AI-supported equipment or machinery used to manufacture products. The loan is built for fixed assets, so it fits a CNC line, a press, a packaging system or a new production building. It does not fit payroll, raw materials or inventory. This guide explains what qualifies, how the financing is structured, what it costs and how to apply.
Fbdc
Finance Long-Term Manufacturing Equipment
FBDC offers SBA 504 financing for heavy machinery and equipment, with down payments as low as 10% and long-term fixed rates.
The test is useful life, not industry label. SBA’s 504 loan page names long-term machinery and equipment with at least 10 years of useful remaining life as an eligible use. Heavy production equipment usually clears that bar. Typical examples include:
Equipment that wears out in five or six years, such as light tools, small vehicles or computers, generally does not meet the 10-year standard. If a project mixes both kinds, talk to us about how to split it. Some items can sit in a 504 project and others may need different financing.
The same loan can also pay to buy, build, renovate or refinance the plant itself. Many manufacturers combine a building purchase with the equipment that goes inside it. Our guide to SBA 504 financing for Florida manufacturers buying equipment walks through that kind of project.
SBA states that 504 loans cannot be used for working capital or inventory. Plan separate funding for raw materials, wages and operating cash. If working capital is your main need, a 504 loan is not the right tool, and we will tell you so in the first conversation.
According to SBA, the business must:
Non-profits are outside the program, which is why FBDC works with for-profit companies. For a Florida-specific look at these checks before you contact a CDC, read four eligibility checks before a CDC. SBA’s rules also change from time to time, so our summary of recent SBA qualification updates is a useful companion.
Startups are not shut out. If you are a newer company buying equipment, expect to document your plan and equity carefully. We cover that in what SBA 504 startups must document.
A 504 project normally has two loans behind it, plus your own equity. That is how the program keeps the borrower’s cash requirement low.
PieceRoleNotesYour equityDown paymentOur program offers down payments as low as 10%Bank or other first lenderLarger share of the projectSet by the lender’s termsCDC/SBA portion (debenture)Second loanFixed rate, long term
The federal rules, 13 CFR Part 120 Subpart H, state that a 504 loan generally may not exceed 40 percent of total project cost plus 100 percent of eligible administrative costs. SBA may authorize an increase up to 50 percent for good cause shown. The same regulation sets a minimum 504 loan of $25,000.
The minimum equity contribution can be higher in some cases, and our guide to 15% to 20% down for startups explains when. For a Florida-focused example of the low-down-payment approach, see cutting long-term equipment costs with 10% down.
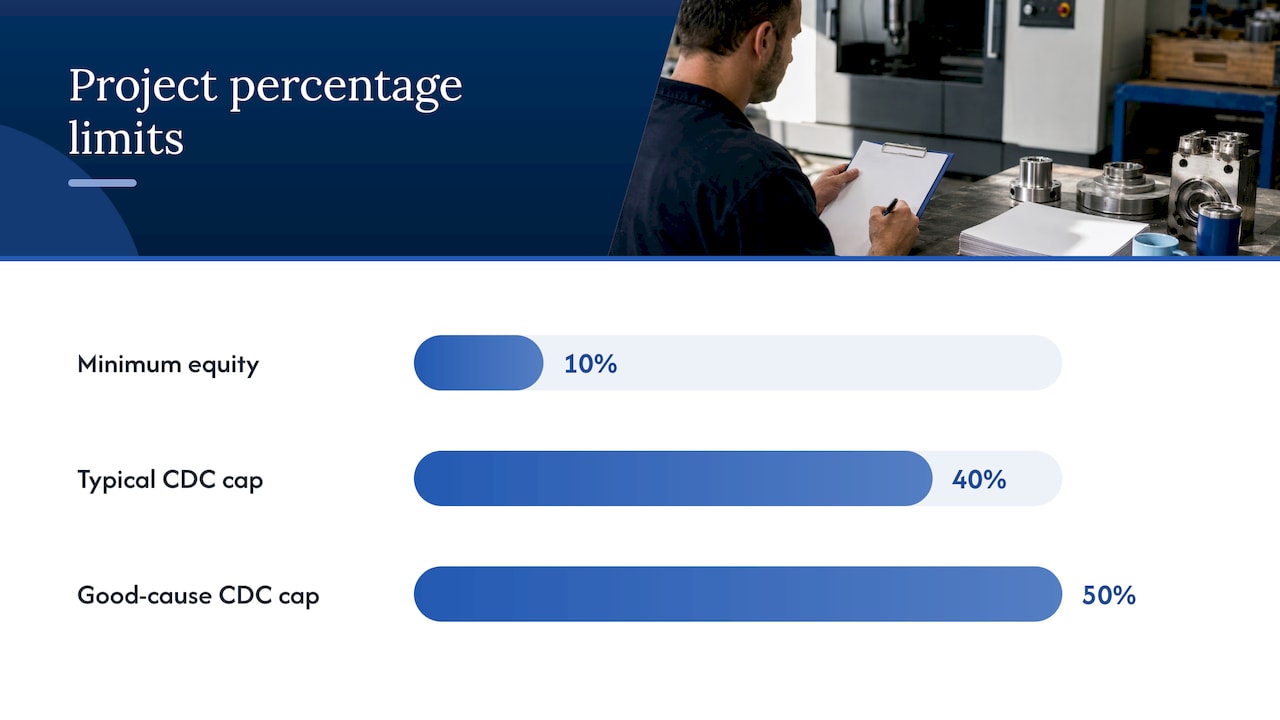
Suppose a Florida fabricator plans a $1,000,000 equipment purchase. Using the 40 percent ceiling from the regulation, the CDC/SBA portion could be up to $400,000, before eligible administrative costs. A first lender could provide the larger remaining share, and the borrower supplies the equity. The exact split depends on the project, the borrower’s profile and the first lender. These figures are illustrative only and are not a quote.

SBA states that 504 loans are available with 10-, 20- and 25-year maturities, and that the interest rate is pegged to an increment above the current market rate for 10-year U.S. Treasury issues. Once the loan is funded, the rate on the CDC/SBA portion is fixed, so that part of your payment does not move.
The maturity choice matters more than most borrowers expect:
A good rule is to match the term to the useful life of the asset and to what your cash flow can carry. Two of our guides cover this in detail: matching equipment loan term to useful life and cash flow and how 10, 20 and 25 year terms work.
SBA sets its 504 fees by federal fiscal year. NAGGL reported that the FY 2027 7(a) and 504 fees apply to loans receiving an SBA loan number on or after October 1, 2026. In recent schedules SBA has reduced or waived certain fees for manufacturers, and the details depend on your industry classification and the approval date. Because the rules turn on the fiscal year, do not budget from an old article. Ask your CDC to confirm which schedule applies to your loan.
Other costs to plan for:
Manufacturers often compare a 504 loan with a 7(a) loan, a conventional mortgage or an equipment lease. In short:
SBA says 504 loans are available exclusively through CDCs. You can find one in your area or contact your local SBA office. In Florida, that is where we come in. The usual path looks like this:
When real estate is part of the project, our CDC lender checklist for a 60 to 90 day close shows what to prepare. If construction is involved, read how to avoid extra interim interest on SBA 504 construction.
Do not sign a binding purchase order or take delivery before talking to a CDC. The financing structure, and in some cases eligibility of the expense, depends on how and when the purchase is made. A short call before you commit costs nothing and can keep a project on track.
We have spent more than 35 years financing small businesses in Florida, and equipment projects are among the ones we enjoy most. A manufacturer who buys a new production line usually adds shifts, hires people and moves up in the market. A loan that keeps the down payment low leaves cash in the business for the things a 504 loan cannot pay for, such as materials and payroll.
Our approach is simple. We look at the equipment, its useful life and your cash flow, then recommend the term that fits. We aim to give you certainty about the structure early, and our staff are experienced in guiding first-time borrowers through each step.
For manufacturers, we see the 504 program as a strong fit: down payments as low as 10%, long-term fixed rates and a structure designed for assets that will serve you for a decade or more. If your project needs a faster path, our bridge loan program can help while the permanent financing is finalized.
PHENYX
We provide SBA 504 financing for Florida businesses buying machinery, equipment and real estate. If you are a veteran, our VetLoan Advantage Plus program is built for you. For smaller projects, see our Direct Lending Program, and for timing pressure, the 504 Velocity Bridge Loan Program.
Ready to talk through your project? Start on our SBA 504 loan page or find your nearest contact on SBA 504 loans anywhere in Florida, and we will walk you through the next step.
SBA’s standard is long-term machinery and equipment with at least 10 years of useful remaining life, so what matters is the remaining life, not whether it is new. Used equipment with enough life left may be considered. Send us the equipment details and we will review how it fits.
No. SBA states that 504 loans cannot be used for working capital or inventory. They are for fixed assets such as real estate and long-term equipment. Plan separate funding for operating needs.
The federal regulation sets a minimum 504 loan amount of $25,000. For smaller projects, ask us about our Direct Lending Program.
SBA updates its fee schedule each federal fiscal year, and recent schedules have included relief for manufacturers. The right answer for your loan depends on your industry classification and approval date, so we confirm it with you at the start of the process.

